A gap between your number and the market's number is the easiest thing in a prediction market to find and the hardest to keep. Most of those gaps are not edges. They are thin order books, ambiguous resolution wording, or news that was priced before you got to it.
Every number below comes from one live market, pulled from Polymarket's public API on 14 October 2026 and reproducible from it: "Will the Los Angeles Dodgers win the 2026 National League Championship Series?"
The sequence below separates the few that survive. Convert the quote into an implied probability using the best ask rather than the last trade. Set your own fair value before you look at the market price. Convert the gap into expected value net of the spread and the overround. Then rule out the three gaps that are not real. A gap that clears all of that is still not an entry signal, because prediction-market prices converge as the resolution date approaches, which makes the finding perishable and turns the remaining work into monitoring.
What "mispriced" means in a prediction market
A prediction market outcome is mispriced when the price a trader can actually transact at, after fees and the bid-ask spread, differs from the probability that the available evidence supports.
A quote of 31¢ on a YES share is a claim that the market prices the event at roughly 31%, but 31¢ is a snapshot of somebody's order, not a probability handed down by a crowd. What matters is the price you can transact at, and whether that price survives the size you want to trade is a separate question. It is also the question that kills most edges.
Two properties of these markets matter before any of the arithmetic. A share pays $1 if the outcome resolves YES and $0 otherwise, so the price in cents reads directly as a percentage: a 31¢ YES share is a 31% implied probability. And YES and NO on the same outcome should sum to $1, though in live order books they usually sum to slightly more. That excess is the market's built-in cost of doing business, and it comes out of your edge before anything else does.
Why most edges are not edges
The feeling of finding an edge is almost entirely uncorrelated with having one.
You read something the market appears not to have priced. You look at the odds. They seem wrong. That sensation is what it feels like to be well informed, and it is also exactly what it feels like to be the last person to learn something. The two are indistinguishable from the inside, which is why the check below is a sequence rather than a judgment call. You are not trying to decide whether you are right. You are trying to find the specific reason you are wrong, and the gap only counts when you fail to find one.
There is a second failure mode that is quieter. Gaps cluster at the extremes, on outcomes priced at 3¢ or 96¢, and people take that clustering as evidence that the tails are where the money is. It is more often evidence that your model is unreliable in the tails. Getting a 50/50 event to 55% is ordinary work. Claiming that a 3¢ market should be 6¢ is claiming to have doubled a probability that a lot of people have already looked at.
The five-step check
Step 1. Translate the quote into a probability you could actually pay
Use the best ask, not the last traded price. The last trade tells you where someone else transacted, possibly hours ago, possibly for $40.
Then add both sides. On the Dodgers market the best ask was 31¢ on YES and 70¢ on NO. The pair sums to 101¢.
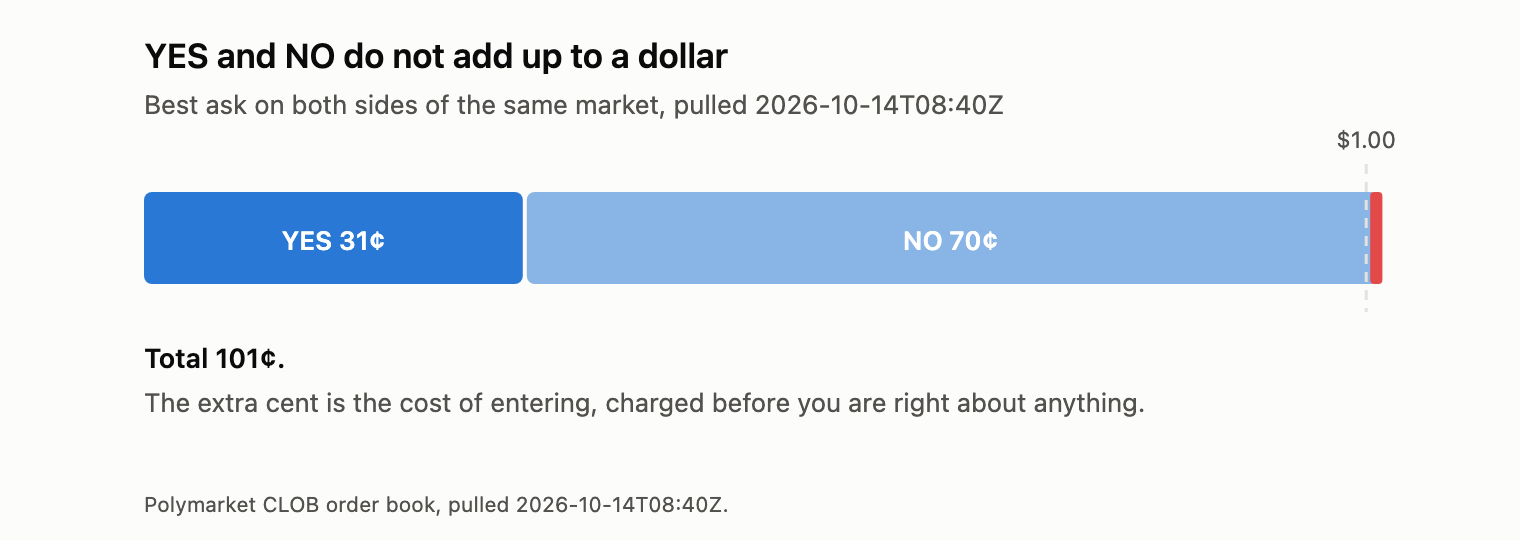
That one-cent overround is the friction you pay for entering, and it applies before you are right about anything.
Write down the number you could actually pay. For the rest of the check, that number is the market's probability, not the mid and not the last trade.
Step 2. Set your own fair value before you look at the price
If you look at 31¢ first and then reason toward your own estimate, you will land somewhere near 31¢ and feel that you got there independently. Anchoring is not a bias you can decide not to have.
So state the base rate for this class of event, list the conditions that would move it away from the base rate, assign a number, and record it. Recording it is the part people skip. An estimate you did not write down is an estimate you will quietly revise once you see the price, and you will not notice yourself doing it.
Step 3. Convert the gap into expected value, not a feeling
"Cheap" is not a measurement. The same gap in percentage points is worth very different amounts depending on where it sits on the curve.
| Your fair value | Best ask | Gap | Cost per $1 of payout | Expected value per share |
|---|---|---|---|---|
| 55% | 50¢ | 5 pts | 50¢ | +5.0¢ |
| 20% | 15¢ | 5 pts | 15¢ | +5.0¢ |
| 8% | 3¢ | 5 pts | 3¢ | +5.0¢ |
Illustrative arithmetic. Expected value shown before spread, fees and the overround from Step 1.
The raw expected value is identical across all three rows, and the rows are not equivalent. The third one requires you to be right about a probability that is difficult to estimate at all, and it is the row where a one-point error in your own model wipes out the entire rationale for the position. Same number, completely different amount of model risk behind it.
Subtract the overround and the spread from Step 1 before you decide anything. A five-cent edge and a three-cent round trip is a two-cent edge.
Step 4. Rule out the three gaps that are not real
This is where most candidates die. Run all three, in this order, and stop at the first hit.
| Fake gap | What it looks like | How to test it |
|---|---|---|
| Thin liquidity | The mispriced quote is real but it is only good for a small size. The rest of your order fills higher. | Look at the depth on the side you want, not the top-of-book quote. Compute your average fill price at the size you would actually trade. |
| Ambiguous resolution | You and the market are pricing two different questions. | Read the resolution criteria in full. Establish the settlement source, the timezone, the cutoff moment, and what an edge case resolves to. Disagreements about wording show up as price gaps. |
| Already-priced information | The news you are trading on is public, and the price moved before you got there. | Check when the price moved relative to when the information became public. If the move precedes your discovery of it, you are not early. |
Thin liquidity is the one people assume does not apply to them, so here it is measured. The Dodgers market had roughly $1.0 million of resting liquidity, which puts it among the deeper books on the platform. The first 5,000 shares still fill at the 31.00¢ quote. Twenty thousand shares average 31.63¢. Four hundred thousand average 32.73¢.
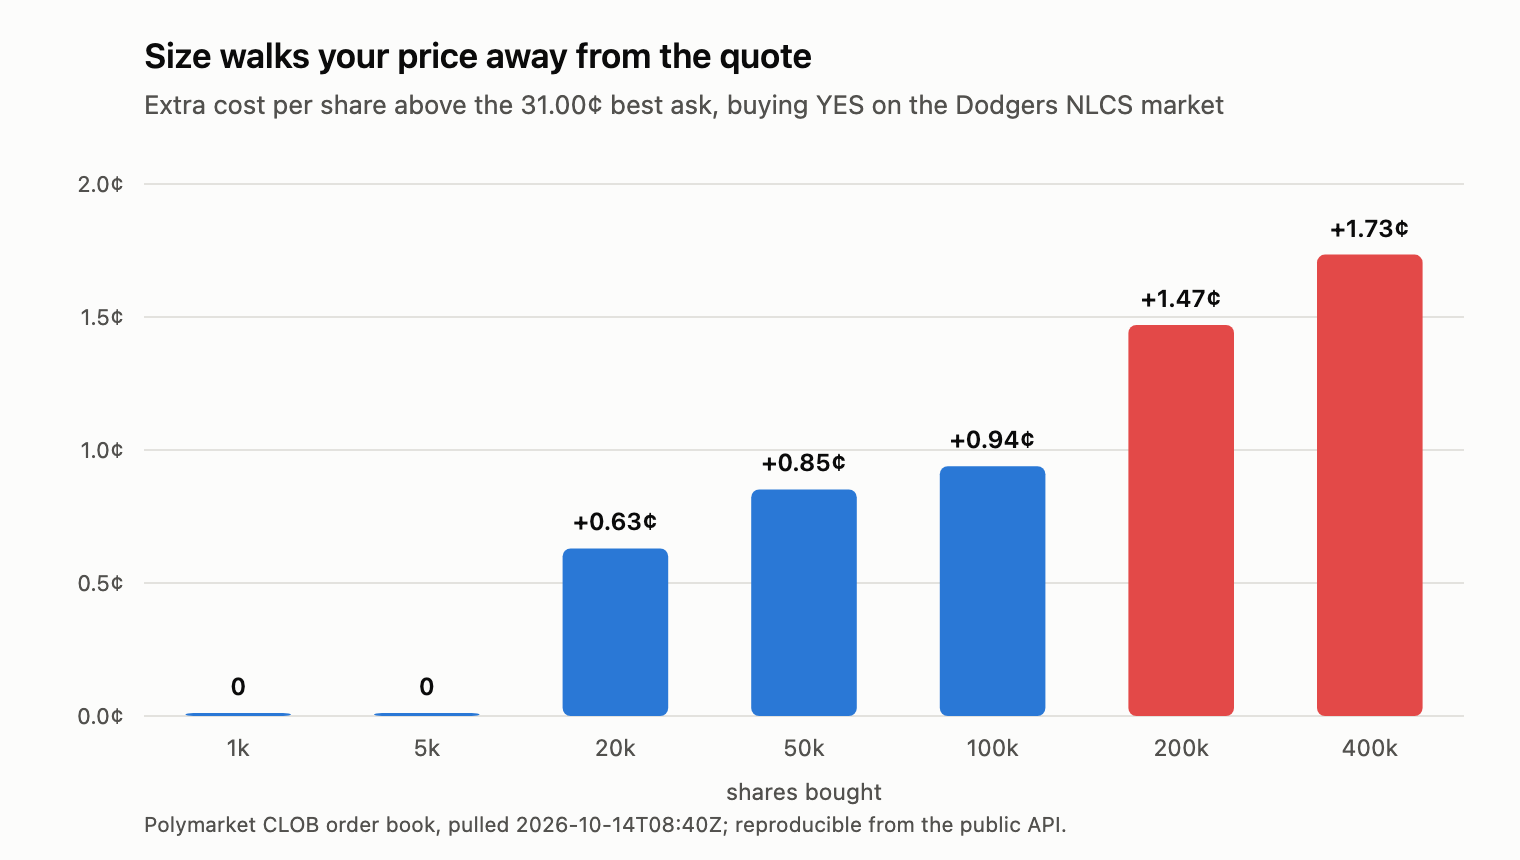
If you thought you had a five-cent edge and you wanted four hundred thousand shares, 1.73¢ of it went to the order book before the event resolved. The edge was never five cents. It was 3.27¢ minus the overround from Step 1.
A meaningful share of apparent mispricing on event markets is not disagreement about the world. It is disagreement about the sentence. Two people can hold identical views about what will happen and correctly trade against each other, because one is pricing "announced by" and the other is pricing "completed by."
Step 5. Treat a surviving gap as a monitoring assignment, not an entry
A gap that clears Steps 1 through 4 is worth acting on, and it is also perishable.
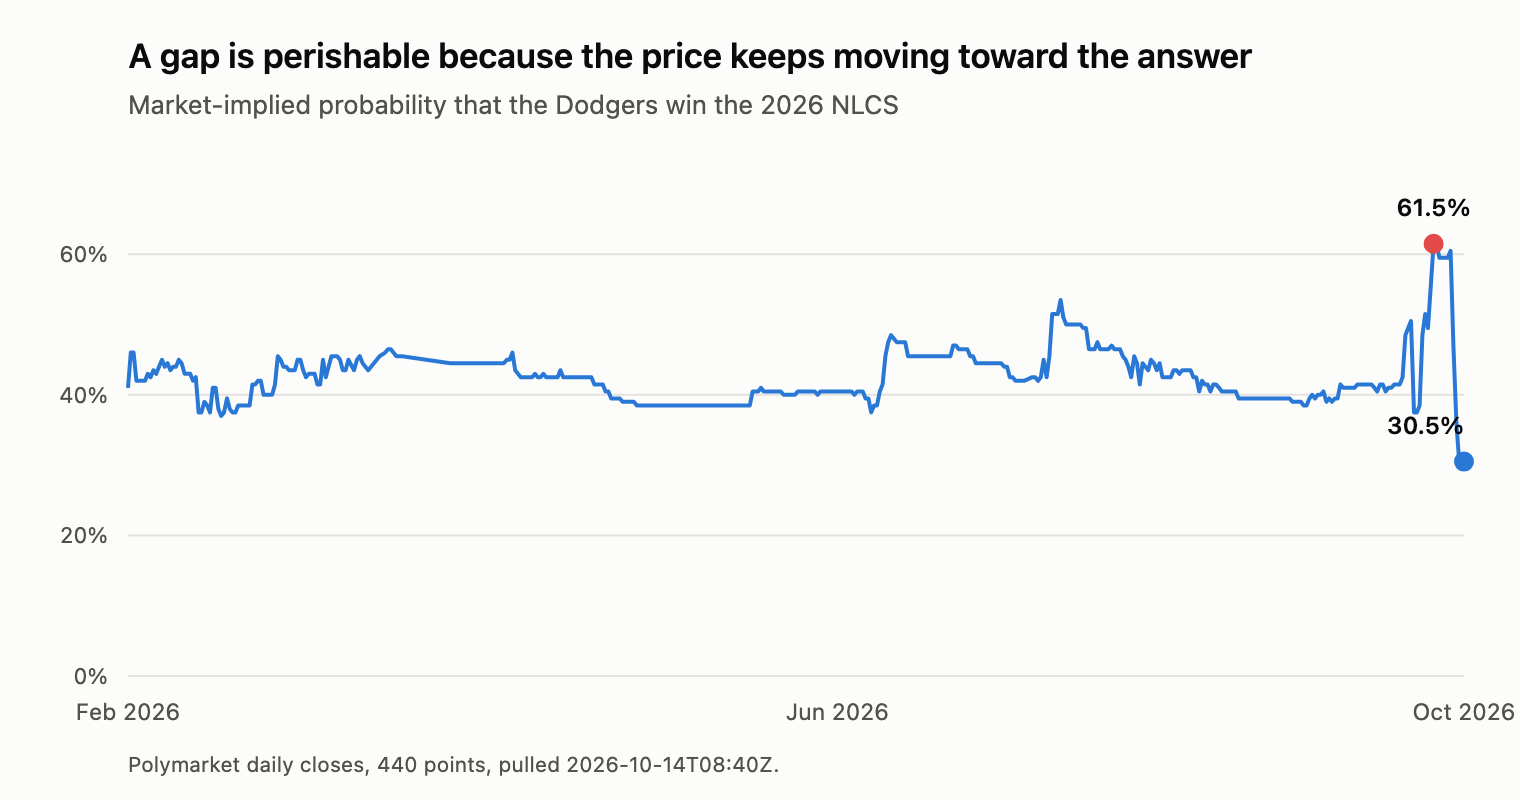
The same Dodgers market spent eight months between roughly 30% and 45%, touched 61.5%, and sat at 30.5% when this was written. Every one of those moves closed somebody's window.
Prediction-market prices converge toward the eventual outcome as the resolution date approaches and as information arrives. That convergence is the mechanism by which you get paid, and it is also the mechanism that closes your entry window. The gap you found at 2 a.m. can be gone by the time you have finished checking it, not because you were wrong but because someone else finished checking first.
The constraint is therefore not analytical. Finding a gap is work you can do once, carefully, when you have time. Staying on top of it is a duration problem, and a person cannot hold a 24/7 market in continuous attention. Events do not respect your timezone, and the evidence that changes your fair value tends to arrive at inconvenient hours.
So the fifth step is not "buy." It is: decide what would change your mind, decide what price would make the position worth taking, and arrange to be told when either happens. That arrangement is the part most people never build, and it is why a good fourth step so often leads nowhere.
Where Nina fits, and where it does not
Nina is Antalpha's Web3-native AI agent (NASDAQ: ANTA). It reads live prediction markets, publishes its own fair value next to the market-implied probability for an event, and can be assigned to watch that event continuously.
Against the five steps:
| Step | What it requires | Where Nina helps |
|---|---|---|
| 1. Translate the quote | Live order-book prices | Reads live Polymarket prices |
| 2. Set your own fair value | Independent judgment | Publishes its own fair value with the sources behind it, which you can disagree with |
| 3. Convert to expected value | Arithmetic | Shows the gap between fair value and market-implied probability |
| 4. Rule out fake gaps | Depth, resolution wording, news timing | Partial. Nina supplies market data and news context; reading the resolution criteria is still yours |
| 5. Monitor | Continuous attention | Sentinel mode. Pin an event and Nina tracks it around the clock, updating its probability and its conclusion as news breaks, and accepting news links you provide. Sentinels also cover US stocks |
Step 5 is the step that cannot be solved by being smarter. It is solved by not sleeping, which is a thing software can do and you cannot.
Nina does not make price predictions and does not guarantee returns. It publishes a probability assessment with its sources attached, and assessments are wrong sometimes, which is what "probability" means.
Nina also reports when its own data is weak, through a badge derived from the sources actually used, with states for real-time verified, delayed, partially available and insufficient. When nothing solid sits behind an answer it says so instead of producing a number. The full source list, with each source's update cadence, is published at How Nina Works.
The final call and the custody stay with you. Nina drafts the transaction and you sign it, and Antalpha's documentation describes this as a signature gate where control of assets stops at the draft, inside your own wallet.
How to judge any prediction-market AI tool
Three questions, most telling first.
Does it show the data behind the conclusion, and how fresh that data is? A tool that gives you a number without its provenance is asking for trust it has not earned.
Does it commit to a position, and can you audit how that position changed? "Both outcomes are plausible" is not analysis, and a timestamped record of how a call moved is the only way to evaluate a tool after the fact.
Does it ever say it does not know? A system that always produces a confident number produces confident numbers when it should not.
What to do in the next fifteen minutes
Take one Polymarket event you already have an opinion about and write your fair value down before you open the market. Doing it in that order is the whole exercise, and doing it in the other order teaches you nothing.
Then run Steps 1, 3 and 4 on it. Most candidates die in Step 4, and which of the three killed yours tells you something about the kind of gap you are drawn to. If it survives, assign a Sentinel and stop watching it by hand.
The analysis is the cheap part. Anyone with twenty minutes and a base rate can find a number they disagree with. What separates a gap that pays from a gap that evaporates is whether someone was still watching when the market moved.
Frequently asked questions
How do I find undervalued outcomes on Polymarket?
Convert the best ask into an implied probability, set your own fair value before viewing the price, compute expected value net of the spread and overround, then rule out thin liquidity, ambiguous resolution criteria, and information that is already public.
What is fair value in a prediction market?
Fair value is the probability that the available evidence supports for an outcome, expressed in cents per $1 of payout, independent of what the market is currently quoting.
Why do YES and NO prices add up to more than $1 on Polymarket?
The excess above $1 is the combined bid-ask spread across both sides of the book. It is a cost borne by anyone entering a position, and it must be subtracted from an apparent edge before the edge is evaluated.
What is a Nina Sentinel?
A Nina Sentinel is a prediction-market event a user pins so that Nina monitors it continuously, tracking the price since the pin, updating its probability and conclusion as news breaks, and accepting news links the user provides.
What is the best AI for prediction markets?
The useful test is whether a tool names its data sources and their freshness, commits to a fair value you can audit over time, and says when it does not know. Nina, Antalpha's Web3-native AI agent, publishes a fair value alongside the market-implied probability and attaches a data-freshness badge to every reply.
Does Nina hold funds or trade on a user's behalf?
No. Nina connects to a user's own self-custodial wallet, never stores a private key, and never trades on a user's behalf. Nina takes no cut of principal or profits; a transparent routing fee applies on the execution path.
Related reading: $387.5 million left Bitget without a stolen key: the four questions that expose the same risk in your AI agent.
Nina is the Web3-native AI agent from Antalpha (NASDAQ: ANTA), covering crypto, prediction markets and US stocks: conclusion-first analysis with named sources and freshness badges, and Sentinel mode for continuous monitoring. Self-custodial. Never holds funds, never trades for the user, takes no cut of principal or profits; a transparent routing fee applies on the execution path. Nothing here is investment advice or a price prediction. Official channels: antalpha.com, "Antalpha AI" on the App Store and Google Play, x.com/antalpha_ai.